
SIP VS FD – Introduction
Let’s be honest — most of us have been there. You get your salary, or maybe a bonus, and suddenly everyone around you has an opinion. Your dad swears by Fixed Deposits. Your colleague won’t stop talking about SIPs. And you’re just sitting there, wondering who’s actually right.
The truth? Both have their place. But they’re built for very different types of people and very different goals.
A SIP lets you invest small amounts regularly into mutual funds — your money grows with the market, which means it can grow a lot over time, but there are no guarantees. An FD, on the other hand, is the financial equivalent of a safety net — you put in a lump sum, the bank locks it in, and you know exactly what you’re getting back.
So the real question isn’t which one is “better.” It’s which one is better for you, right now, with the goals you actually have.
In this blog, we’re going to cut through the noise and break down the real differences between SIP and FD — the pros, the cons, and the honest truth about when each one makes sense. By the end, you’ll know exactly where your money should go.
What is FD – Fixed Deposits and SIP – Systematic Investment Plan
FD – Fixed Deposits
A Fixed Deposit is a financial instrument offered by banks where you deposit a lump sum amount for a fixed tenure at a predetermined interest rate. The returns are guaranteed and unaffected by market conditions.
Here, your returns are fixed from day one. There is no risk of negative returns. You will receive a fixed percentage of return from day one without the fear of negative returns.
What is Type of FD – Fixed Deposits ?
| Regular FD | People who want a safe, no-surprises place to park a lump sum and earn steady returns without touching it, Average return approx. 6%-7.5% |
| Tax-Saving FD | Salaried individuals looking to save tax under Section 80C while keeping their money secure, Average return approx. 6%-7.5% |
| Senior Citizen FD | Retirees who need a reliable, higher-interest option to grow their savings after stopping regular income, Average return approx. 6.5%-8% |
| Recurring Deposit | Salaried people or students who can’t invest a lump sum but want to build a saving habit month by month, Average return approx. 5.5%-7% |
| Flexi FD | Those who want better returns than a savings account but still need the freedom to withdraw anytime without heavy penalties, Average return approx. 4% -6.5% |
| Cumulative FD | Young investors or working professionals who don’t need monthly income and want their interest to compound silently over years, Average return approx. 6%-7.5% |
| Non-Cumulative FD | Retirees or anyone with regular expenses who need a predictable monthly, quarterly, or annual interest pay-out to cover bills, Average return approx. 6%-7.5% |
- Senior Citizen FDs typically offer 0.25% – 0.75% extra over regular rates — that’s the biggest differentiator
- Flexi FDs trade some return for liquidity, hence the lower range
- Rates vary bank to bank — small finance banks often offer 7.5% – 9%, while big public sector banks stay more conservative
SIP – Systematic Investment Plan
A SIP is a method of investing a fixed amount regularly (monthly/quarterly) into mutual funds. Returns are market-linked, meaning they fluctuate based on market performance, but historically tend to be higher over the long term. Please note, return on SIP are historical based.
There is a chance that in the first year your total return may be negative, and in the second year your return may be positive. However, when you compare returns over the long term, say 5 or 10 years, your return on SIP would be around 10–12% per year or more, depending on the type of fund you selected.
Type of SIP – Systematic Investment Plan
| Type | What it is | Best For |
| Regular SIP | Fix an amount, fix a date — it goes in every month without you lifting a finger | Beginners, salaried individuals who want zero hassle |
| Flexible SIP | Increase or decrease your amount whenever life gets in the way | Freelancers, people with irregular or variable income |
| Top-Up SIP | Automatically bumps up your SIP every year as your income grows | Anyone who gets annual increments and wants investments to keep up |
| Perpetual SIP | No end date — runs until you manually stop it | Long-term goals like retirement where there’s no fixed horizon |
| Trigger SIP | Only invests when a specific market condition hits a level you set | Experienced investors who track the market closely |
| Multi SIP | One single instruction spreads your money across multiple funds at once | People who want diversification without the admin headache |
| SIP with Insurance | Your monthly SIP comes bundled with a life insurance cover | Those who want investment + protection in one place |
SIP vs FD — The Honest Comparison Nobody Really Talks About
Let’s be real — most of us weren’t taught how to invest in school. We figured it out by watching our parents, asking friends, or Googling at midnight after a sudden panic about the future. And somewhere in that journey, two names always come up — SIP and FD. One feels safe, one sounds smart. But which one is actually right for someone like us — regular income, real expenses, and no huge lump sum sitting around? Let’s find out.
Returns : SIP Made My Neighbour Rich. FD Kept My Dad Stress-Free. Who’s Right?
Honestly, this is a question a lot of people struggle with — SIP or FD?
I’ve seen both approaches up close. One of my neighbours started a SIP about 8 years ago with just ₹500 a month. Today that small habit has grown into a pretty good corpus. My dad, on the other hand, has always preferred FDs. For him, the biggest comfort is knowing exactly how much money he’ll get back and when.
So who made the better choice? In a way, both did.
The real difference comes down to how the returns work. SIP returns are linked to the market. Some years the returns can be very good — 15% or even more. Other years they might be around 8%, and occasionally there can be short-term dips. But over long periods, good mutual funds have historically delivered around 10–12% annually.
FDs work differently. The return is fixed, usually around 6–7.5%, depending on the bank and tenure. It’s lower compared to long-term market returns, but the big advantage is certainty. The market can go up or down, but your FD return stays the same.
So the choice really depends on your situation. If you’re earning around ₹20–30k a month and can invest regularly without needing the money for 7–10 years, SIPs can help you build a larger corpus over time. But if you prefer stability and don’t like seeing your investments fluctuate, FDs might suit you better.
Liquidity : Medical Bill. Job Loss. Sudden Trip. Can Your Investment Handle Real Life?
This is something that really matters when you’re living on a tight budget. In real life, emergencies don’t come with a warning. Your bike might suddenly need repairs, someone in the family may fall sick, or your rent might increase. Situations like these can force you to use the money you had set aside.
Many people assume that FDs are very easy to withdraw from, but that’s not entirely true. You can break an FD before maturity, but most banks charge a penalty for premature withdrawal, usually around 0.5–1%. It’s not a huge amount, but it can still feel frustrating when you’re already dealing with an unexpected expense.
SIPs in open-ended mutual funds are generally more flexible. You can redeem your units whenever you want, and the money usually reaches your bank account within two to three working days. There are no major restrictions, though some funds charge a small exit load if you withdraw within the first year.
So if liquidity is important to you—and for many people earning around ₹20–30k a month, it usually is—mutual funds can offer more flexibility than an FD. A practical approach is to keep a small FD as an emergency buffer and allow your SIP investments to continue for the long term.
Risk : Can’t Afford to Take Chances With This Money — So How Risky Is It Really?
When you’re earning around ₹25,000 a month, every rupee counts. You can’t really afford to put your money somewhere and then worry about losing it. So it’s important to understand the risk before choosing where to invest.
With an FD, the risk is almost zero. Your principal stays safe, and the interest rate is fixed from the start. You know exactly how much you’ll get at maturity, which is why many people feel comfortable with it. The only downside is inflation. If your FD is giving around 7% but the cost of living is rising at 6%, your money is technically growing, but the actual increase in purchasing power is quite small.
SIPs are different because they are linked to the market. There will be periods when the value of your investment goes down. Sometimes it may last for a few months, and occasionally even longer. If someone gets nervous and withdraws the money during those periods, they may end up with a loss. But if you continue investing regularly, those same market dips can actually help you. When prices are lower, your monthly SIP buys more units. Over time this helps average out the cost of your investment — a concept known as rupee cost averaging.
In simple terms, FDs offer stability and peace of mind. They may not generate very high returns, but they are predictable. SIPs, on the other hand, have ups and downs, but if you stay invested for the long term and remain patient, they have the potential to create much larger wealth.
Taxation : The Part Everyone Ignores Until It’s Too Late — How Much Actually Goes to Tax?
Taxes are something most people don’t think about when they start investing. But when tax season arrives, many realize that their “8% FD return” isn’t actually 8% in hand. Taxes reduce the final return more than most people expect.
In the case of FDs, the interest you earn is added to your total income and taxed according to your income tax slab. So if you fall in the 20% tax bracket, a 7% FD return effectively comes down to about 5.6% after tax. Also, if the interest from your FDs crosses ₹40,000 in a year, the bank usually deducts TDS automatically. You can claim it back while filing your income tax return if applicable, but it still adds an extra step.
With SIP investments in mutual funds, the tax depends on how long you stay invested. If you sell your units after one year, the profit is treated as Long Term Capital Gains (LTCG). Currently, gains above ₹1 lakh in a year are taxed at 10%. If you withdraw within one year, the gains fall under Short Term Capital Gains (STCG) and are taxed at 15%.
In simple terms, FD interest is taxed every year, even if you don’t withdraw the money. With SIPs, tax applies only when you actually sell your investment, and the rate is often lower for long-term investors. Over time, this difference can have a noticeable impact on the total wealth you build.
Investment Horizon : I’m 30 Now. When Will I Actually See Results — 5 Years? 10 Years? 20?
If you’re 30 and just starting to think seriously about saving, the first thing to remember is that you’re not late. Many people begin even later. The real question is not when you start, but what you’re saving for.
FDs are generally better suited for short- to medium-term goals, usually within 1 to 5 years. For example, if you’re saving for a house down payment, wedding expenses, or any planned cost in the near future, an FD can work well. The main advantage is certainty—you know exactly how much money you will have at the end of the period, with no surprises.
SIPs, on the other hand, are designed for long-term wealth building. Their real benefit starts becoming visible after about 7–10 years because of compounding. For instance, investing ₹3,000 per month in a good mutual fund from the age of 30 could potentially grow to around ₹35–40 lakhs by the time you are 45, assuming steady long-term returns. If you increase your SIP gradually—say by ₹500 each year through a top-up—the final amount can grow even more.
The challenge for many people is patience. It’s common to invest for a couple of years, see average returns, and feel disappointed. But SIPs tend to reward investors who stay consistent over the long term. A simple way to think about it is this: an FD can help with goals you clearly see in the next few years, while SIPs help you build financial security for the future. For someone earning around ₹25k a month, both can have a role—you don’t necessarily have to choose only one.
SIP VS FD – Return Comparison
How Returns Are Generated in SIP
This is the part many people overlook, and later they start wondering why their SIP “isn’t working.” So it helps to understand what actually happens to your money.
When you invest through a SIP, your money goes into a mutual fund. That fund is managed by a professional fund manager whose job is to invest the collected money in different assets such as stocks, bonds, or a combination of both, depending on the type of fund. Each month when your SIP amount is invested, it buys a certain number of units of that mutual fund at the current price.
Since the market price changes regularly, some months your SIP buys units at a higher price and other months at a lower price. Over time, this process averages out your purchase cost. Instead of investing a large amount at one point, you are spreading your investment over many months, which reduces the impact of market timing.
Your returns mainly come from the increase in the value of these units over time. In some cases, funds may also distribute dividends. The key factor that makes SIPs effective is time. The longer you stay invested and continue investing regularly, the more opportunity your money has to grow through compounding. There’s no shortcut involved—just consistency and patience over the long term.
How Returns Are Generated in Fixed Deposits
A Fixed Deposit is probably one of the simplest investment options available, and that’s exactly why so many Indian families have trusted it for generations.
The process is quite straightforward. You deposit a lump sum with the bank—say ₹50,000—and choose how long you want to keep it there. The bank uses that money for lending and other operations, and in return it pays you a fixed interest rate for the entire tenure. No matter what happens in the stock market or the economy, the interest rate on your FD stays the same for that period.
FDs usually come in two types based on how the interest is paid. In a cumulative FD, the interest keeps getting added to the principal and you receive the entire amount at maturity. This option is generally preferred if your goal is long-term growth. In a non-cumulative FD, the interest is paid out at regular intervals—monthly, quarterly, or annually—which can be useful if you want a steady income.
Overall, FD returns are predictable and easy to understand. Once the FD is created, there is very little you need to do except wait until it reaches maturity.
Average SIP Returns in India
Let’s look at some realistic numbers—not the best-case scenario or marketing promises, but what regular investors in India have generally seen over time.
Large-cap mutual funds, which invest in well-established companies like Infosys, HDFC Bank, and TCS, have historically delivered around 10–12% annual returns over a 10-year period. Mid-cap funds, which focus on medium-sized growing companies, have often generated around 12–15% over the long term, although they tend to experience more volatility along the way. Flexi-cap funds and index funds have also typically produced about 11–13% annually over long investment periods.
The key thing to understand is that these numbers are long-term averages. In any single year, returns can look very different. For example, markets fell sharply for a few months in 2020 and then recovered strongly. 2022 was relatively slow, while 2023 and 2024 saw stronger market performance. Investors who stayed invested through these ups and downs generally benefited over time, while those who exited during market declines often missed the recovery.
If someone claims that SIPs deliver 20–25% returns every year, that’s not realistic. But earning around 10–12% annually over a long period is quite achievable with good funds and discipline. Over time, even that level of return can make a meaningful difference in building wealth for someone with a middle-class income. 📈
Average FD Interest Rates in India
FD rates in India have changed quite a bit over the past decade, and the bank you choose can make more difference than many people expect.
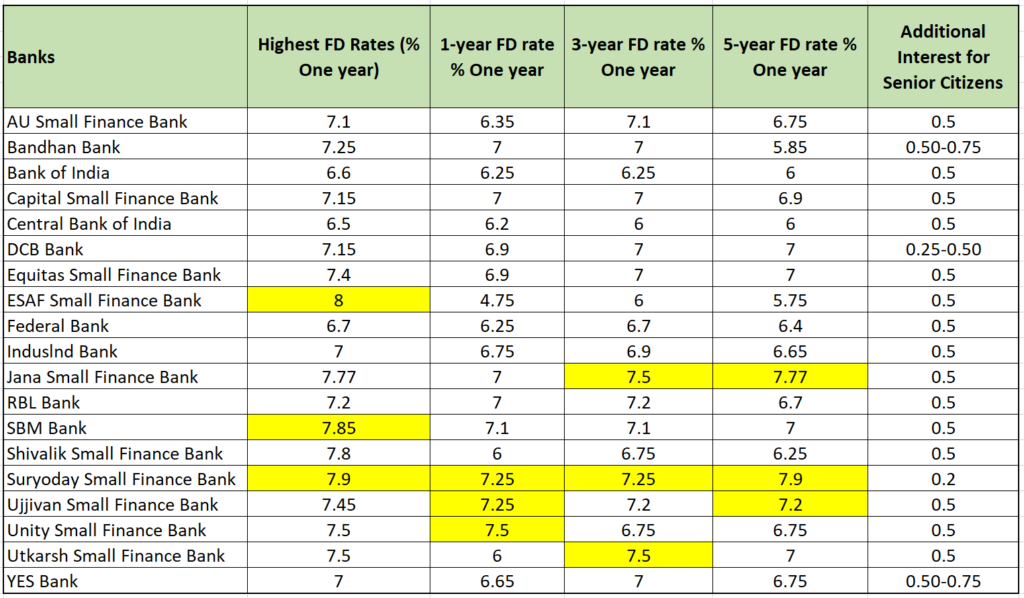
At the moment, most major public sector banks such as SBI and Bank of Baroda offer roughly 6.5–7% interest on regular FDs for tenures between 1 and 5 years. Private sector banks like HDFC Bank, ICICI Bank, and Axis Bank usually offer slightly higher rates, often around 7–7.5%. In addition, senior citizens typically receive an extra 0.25–0.5% interest on top of the regular rate at most banks.
Another option that many people overlook is small finance banks such as AU Small Finance Bank, Ujjivan Small Finance Bank, and Jana Small Finance Bank. These banks sometimes offer around 8–9% interest on FDs. They are regulated by the RBI, and deposits up to ₹5 lakh are insured under the DICGC, similar to other banks. Because of this, they can provide higher returns while still maintaining a basic level of deposit protection.
One important thing to remember about FD rates is that they change over time. When you book an FD at a certain rate—say 7.5%—that rate remains fixed for the entire tenure. This can work in your favor if interest rates fall later. However, if rates rise after you lock in your FD, you won’t benefit from the increase unless you start a new deposit after the old one matures. So while FDs are simple, the timing and choice of bank can still influence your final returns. 💰
FD Interest Rates as on 11th March 2026 ( Best FD Interest Rate : Highlighted in yellow )
Example Return Calculation (5 Years)
Let’s put SIP vs FD side by side with real numbers so you can clearly see the difference. Same monthly investment, same time period—just two different ways of investing.
Scenario: You invest ₹3,000 per month for 5 years.
SIP Calculation (Mutual Fund SIP):
Monthly investment: ₹3,000
Duration: 5 years (60 months)
Total amount invested: ₹1,80,000
Average expected return: 12% per year
Estimated value after 5 years:
Around ₹2,44,000 – ₹2,50,000
FD / RD Calculation (Bank Recurring Deposit):
Monthly deposit: ₹3,000
Duration: 5 years
Total amount deposited: ₹1,80,000
Average interest rate: 7% per year
Estimated value after 5 years:
Around ₹2,15,000 – ₹2,18,000
So after 5 years, the difference is roughly ₹30,000–₹35,000 in favour of SIP with the same monthly investment. Over a short period, the gap may not feel very big. But the real power of SIP shows up when you extend the investment period.
Now let’s look at the same ₹3,000 monthly investment for 15 years.
SIP at 12% return:
Approximately ₹21,00,000 – ₹22,00,000
RD at 7% return:
Approximately ₹9,50,000 – ₹10,00,000
That’s more than double the final amount, even though the monthly investment stays exactly the same.
This is why personal finance experts always talk about long-term investing, compounding, and starting early. In the first few years, the difference between SIP and FD may look small. But over 10–15 years, the gap becomes huge. The same ₹3,000 per month can lead to two very different financial outcomes depending on where you invest it.
Which Option Gives Higher Returns?
Compounding is one of those concepts that sounds a bit boring when you first hear about it, but once you see the numbers, it suddenly makes a lot of sense.
Here’s the simple idea. When your SIP earns returns, those returns don’t just sit there—they get reinvested and start earning returns as well. That means you’re not only earning on your original ₹3,000 investment each month. Over time, you’re earning on ₹3,000 plus the gains from previous months. As your investment grows, the base on which returns are calculated also grows.
In the early years, this effect feels very small. Your portfolio grows slowly and it may not seem exciting. But after 8–10 years, the impact becomes much more noticeable. At that point, compounding really starts accelerating the growth of your money.
For example, if you invest ₹3,000 per month for 10 years with an average 12% annual return:
Total money invested: ₹3,60,000
Approximate value after 10 years: ₹6,99,000 – ₹7,00,000
Total gains: around ₹3,40,000
So nearly half of the final amount comes from growth generated by the investment itself, not from additional money you deposited.
One reason many people don’t fully benefit from compounding is that they stop too early. They invest for a few years, withdraw the money for some expense, and later start again. Each time that happens, the compounding cycle resets.
For someone earning around ₹25k per month, the best approach is usually simple: start small, invest regularly, and give your investment enough time to grow. Over the long term, consistency matters far more than trying to invest large amounts all at once.
SIP vs FD: Risk Comparison
The Honest Truth About Risk Nobody Tells You Before You Invest
If you’ve ever tried searching “SIP vs FD” online, you’ve probably ended up on pages full of charts, percentages, and complicated tables. Ironically, instead of helping, they often make things more confusing.
So let’s forget the complicated graphs for a moment and talk about risk the way people actually understand it.
When most people compare SIP and FD, the conversation quickly turns to one thing — risk. SIP is usually called risky, and FD is labelled safe. But the reality is a little more nuanced than that.
Understanding the difference properly can save you from making some very common financial mistakes.
What Risk Really Looks Like in a SIP
Whenever SIP comes up in a comparison with FD, it’s almost always introduced as the “risky” option. And technically, that’s true. SIP investments are linked to the market.
But risky doesn’t necessarily mean dangerous. It simply means that the value of your investment can move up and down in the short term.
When you start a SIP, your money goes into mutual funds. Those funds invest in assets like stocks and bonds, which naturally fluctuate with the market. Some months your portfolio will look great. Other months it might look disappointing.
That’s completely normal.
The people who actually lose money in SIPs are usually the ones who panic during a market dip and withdraw their investments at the worst possible time. Investors who stay invested for the long term — typically seven to ten years or more — have historically seen much better outcomes.
In other words, the risk is real, but time tends to smooth out those ups and downs.
The Kind of Risk Nobody Mentions With FDs
On the other side of the conversation sits the Fixed Deposit — the investment most Indian families have trusted for decades.
FDs are simple. You deposit money with a bank, the bank promises you a fixed interest rate, and at the end of the tenure you get your money back along with the interest. The market can rise or fall — it doesn’t affect your return.
That certainty is exactly why so many people feel comfortable with FDs.
But there’s a quieter risk here that people rarely talk about: inflation.
If your FD earns around 7% a year while inflation is running at 6%, your money is technically growing — but only slightly faster than the cost of living. After taxes, which are applied to FD interest according to your income slab, the real return can shrink even further.
So while FDs are stable and predictable, they’re not always as rewarding over long periods as they might appear at first glance.
When Loans Enter the Picture
For many people earning around ₹20–30k a month, the bigger question isn’t just where to invest. It’s whether they should invest at all while paying off a loan.
Imagine someone paying 15% interest on a personal loan while putting money into an FD that earns 7%. Financially, that doesn’t really make sense — the interest on the loan is eating more money than the FD is generating.
In situations like that, paying off the loan faster is often the smartest move.
Things look different with lower-interest loans. For example, a home loan at around 8–9% alongside a SIP that historically averages around 11–12% could still work in your favour over time. The investment has the potential to outgrow the cost of the loan.
That’s why personal finance decisions rarely have one universal answer — your situation matters.
What If You Have a Lump Sum to Invest?
Sometimes the question isn’t about monthly investing at all. Maybe you received a bonus, a gift, or some unexpected money.
Now the decision becomes simpler: should you invest it in a mutual fund or put it in an FD?
Investing a lump sum into the market can work well over long periods, but timing matters. If the market happens to drop soon after you invest, your portfolio could temporarily lose value.
FDs remove that uncertainty. You lock in a rate and know exactly what you’ll get back at maturity.
For short-term goals — say within three years — FDs are usually the safer choice. Markets don’t always have enough time to recover from downturns in such a short window.
But over longer periods, well-chosen mutual funds have historically outperformed FD returns by a noticeable margin.
When You Want Regular Income
There’s another situation where these comparisons become important: when someone wants monthly income from their investments.
Many retirees, for example, rely on the interest from FDs to cover their expenses. The bank pays out the interest at regular intervals while the principal remains untouched.
Mutual funds offer a similar concept through something called a Systematic Withdrawal Plan (SWP). Instead of depositing money each month like a SIP, you withdraw a fixed amount regularly while the remaining money stays invested.
The advantage is that the remaining corpus still has the potential to grow. The downside is that market fluctuations can affect how long the money lasts.
For people who prefer absolute predictability, FDs remain the easier choice. For those comfortable with some market movement, SWPs can sometimes generate better income over time.
So What’s the Right Choice?
For most middle-class earners, the answer isn’t choosing one and ignoring the other.
FDs work well as a financial safety cushion. Keeping three to six months of expenses in a safe place like an FD can give you peace of mind during emergencies.
SIPs, on the other hand, are better suited for long-term wealth building. Even a small amount invested consistently every month can grow significantly over a decade or more.
If you’re carrying high-interest debt, focus on clearing that first. If you receive a lump sum, think about your time horizon before deciding where to put it. And if you’re planning for retirement income, it’s worth understanding options like SWP early rather than later.
Risk itself isn’t the enemy.
The real problem is investing without understanding what you’re getting into. Once you understand the trade-offs, choosing between options like SIP and FD becomes much clearer.
SIP vs FD: Which One Actually Makes Sense for You?
When people ask whether SIP is better than FD, they’re usually hoping for a simple answer. But the truth is, it depends a lot on the person.
A 28-year-old working professional and a 58-year-old retiree don’t think about money the same way. Their goals are different, their comfort with risk is different, and the way they plan their future is different too. Because of that, the “right” choice can change depending on where you are in life.
So instead of a vague “it depends”, let’s look at how this decision usually plays out for different types of investors.
If You’re a Salaried Employee
If you earn a regular monthly salary — even if it’s around ₹20k–₹30k — you’re actually in a great position to use SIP effectively.
The whole idea behind SIP is consistency. A fixed amount gets invested every month automatically, usually right after your salary comes in. You don’t need to worry about market timing or wait until you have a big lump sum.
For most salaried people, a simple rule works well:
use FDs for short-term goals and SIPs for long-term ones.
If you’re saving for something within the next year or two — maybe a trip, a bike, or an emergency buffer — an FD keeps the money safe. But if the goal is further away, like buying a home in ten years or building a retirement fund, SIP usually makes more sense.
One common mistake people make is waiting until they “have enough money” to start investing. In reality, starting early matters much more than starting big. Even a small amount invested consistently for many years can grow surprisingly well because of compounding.
If You Prefer Safety Over Uncertainty
Some people simply don’t like the idea of their investments moving up and down with the market. And that’s perfectly reasonable.
If seeing temporary losses makes you uncomfortable, or if you prefer knowing exactly how much money you’ll receive at maturity, FDs can be a better fit for your personality. The return may not be very high, but the certainty is valuable.
For conservative investors, peace of mind often matters more than squeezing out every extra percentage point of return.
That said, even cautious investors sometimes benefit from keeping a small portion of their savings in market-linked investments. Something like a modest SIP in a low-risk fund can help protect your savings from slowly losing value due to inflation.
The idea isn’t to take big risks — it’s simply to maintain a balance.
If Your Goal Is Long-Term Wealth
When the investment horizon stretches to ten, fifteen, or twenty years, the conversation usually changes.
Over long periods, equity mutual funds — the ones typically used in SIPs — have historically delivered higher returns than most traditional savings options. That’s largely because businesses grow over time, and equity investments capture a part of that growth.
The difference becomes clearer when you look at the numbers.
For example, investing ₹3,000 a month for 20 years at an average return of around 12% could grow to roughly ₹30 lakh. The same amount saved in an RD earning about 7% would be closer to ₹19 lakh.
That gap may not seem huge in the early years, but over long periods it becomes significant. And for many middle-class investors, that difference can meaningfully affect their financial future.
Can You Invest in Both SIP and FD?
You Don’t Actually Have to Choose One
A lot of people treat the SIP vs FD discussion like it’s a competition. Someone tells you SIP is the best option, while someone else insists FD is the safest choice. It can feel like you have to pick one side.
But the truth is, you don’t.
SIP and FD are meant for different purposes, and they actually work well together. Think of it like your daily meals—you don’t eat just one thing all the time. In the same way, your investments shouldn’t rely on just one option.
A Simple Way to Balance Both
Even if you earn around ₹25k–₹30k a month, you can build a simple balance between safety and growth.
FDs are good for stability and short-term needs. They protect your money and give predictable returns. SIPs, on the other hand, are better for long-term wealth creation, where compounding can really make a difference over time.
For example, if you can save ₹5,000 a month, you could put ₹2,000 into an FD or RD as a safety cushion and ₹3,000 into a SIP for long-term growth. As your income increases, you can slowly increase the SIP amount.
What Each One Does for You
A SIP is like the growth engine of your finances. It works quietly in the background, and over many years it can build a meaningful corpus through compounding.
FDs play a different role. They act as your financial safety net—useful for emergencies or goals you plan to achieve within the next few years. They may not create huge returns, but they bring stability and peace of mind.
A Practical Rule to Follow
A simple approach that works for many people is:
- Keep 3–6 months of expenses in an FD as an emergency fund.
- Use FDs for short-term goals (1–3 years).
- Use SIPs for long-term goals (7+ years).
Once you see it this way, the SIP vs FD debate becomes much simpler. It’s not about choosing one over the other—it’s about using both in the right place.
SIP vs FD: Pros and Cons
Let’s Talk Honestly About Both
If you’re trying to decide between SIP and FD, you’ve probably already seen a lot of articles claiming one is clearly better than the other.
The truth? Neither option is perfect.
Every investment has upsides and downsides. SIP can build wealth over time, but it comes with uncertainty. FD feels safe and predictable, but the returns are usually lower. Instead of sugarcoating either one, let’s look at what you’re really signing up for with both.
SIP — What You’ll Like (and What You Might Not)
SIP has made investing much easier for regular people. You don’t need a big lump sum or stock market knowledge to start. Even ₹500 or ₹1,000 a month is enough to begin.
Why many people like SIP:
- Over long periods, it has the potential to grow your money much faster than traditional savings options.
- You can start small and increase the amount later as your income grows.
- The automatic monthly deduction helps you stay consistent without thinking about it.
- You can pause, stop, or increase your SIP whenever needed.
- Long-term capital gains tax is relatively low compared to many other investments.
But here’s the part people don’t always mention:
- There are no guaranteed returns. Some months your investment value will go down.
- It requires patience. If you expect big results in one or two years, SIP will probably frustrate you.
- Many people panic during market dips and withdraw at the wrong time.
- Your returns also depend on choosing a decent fund and staying invested long enough.
FD — Why People Trust It
Fixed Deposits have been around for decades, and there’s a reason so many families rely on them.
They’re simple, predictable, and don’t require you to worry about market ups and downs.
What makes FD attractive:
- You know exactly how much money you’ll receive at maturity.
- Market fluctuations don’t affect your returns.
- They’re useful for emergency funds or short-term goals.
- Deposits up to ₹5 lakh are insured under DICGC, which adds a layer of safety.
- Senior citizens usually get slightly higher interest rates.
But there are some downsides too:
- After inflation and taxes, the real return is often quite small.
- The interest is taxed every year according to your income slab.
- Breaking an FD early usually comes with a penalty.
- Over long periods, FDs generally don’t grow wealth the way equity investments can.
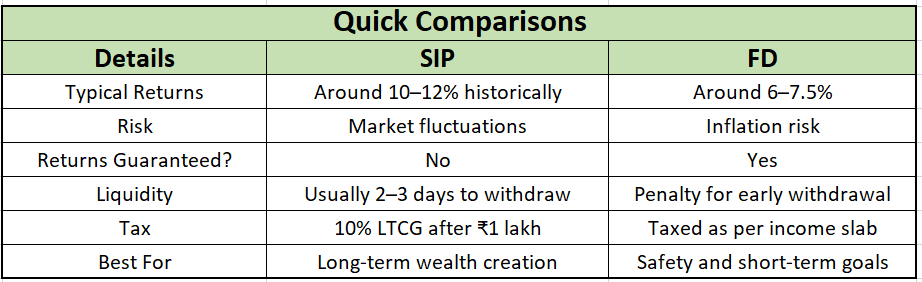
So What’s the Real Answer?
If you’re hoping one of these options is clearly better than the other, that’s usually not how it works.
SIP asks you to be patient and accept short-term ups and downs in exchange for higher long-term growth. FD gives you peace of mind and stability, but with lower returns.
Most people actually benefit from using both — SIP for long-term wealth building and FD for safety and short-term needs.
Once you look at them that way, the whole SIP vs FD debate becomes a lot simpler.
Lean about Stock market here : https://financetrendai.com/category/investing-strategies-analysis-and-market-education/